Short-Long Combination: Short-Cycle Monetization of Large-Diameter Timber
F04 The “Short-Long Combination” Forest Resource Development Model (Part Two: Short-Cycle Monetization of Large-Diameter Timber)
In the previous section we explored how to create short-cycle returns in the canopy scene. The main point was this: do not assume that forestry investment means simply waiting, empty-handed, for the trees to mature and be cashed in. Throughout the growth of young and middle-aged stands, up to the final felling rotation, there is in fact a way to create value every single day.
This section continues along the same line of thinking — using every last part of the forest’s three-dimensional resources — to explore how large-diameter timber can generate short-term returns. (One clarification here: “using every last part” is not the “kill the goose” exploitation of natural resources but maximum-efficiency utilization. On the contrary, the logic of using every part is precisely to cultivate more biodiversity assets.)
How to Create Short-Term Returns from the Main Timber
Timber income is the most basic return in forestry development, built around the harvesting and processing of logs of various diameters. Looking at the basic form of a tree, traditional thinking struggles to see how the main timber could produce short-term returns. Take Korean pine in Northeast China: before its sixty-year final felling rotation, the canopy can deliver an average income of roughly RMB 600 per mu per year from pine-cone collection; yet the main trunk of that timber cannot generate any return at all across those sixty years. Unlike branches, which carry leaves and fruit, or the space beneath the trees, which allows companion planting and intercropping, large-diameter timber offers little prospect of interim income during growth.
So where is the way through?
First, biological companion planting; second, stem extraction; third, using finance to break the deadlock.
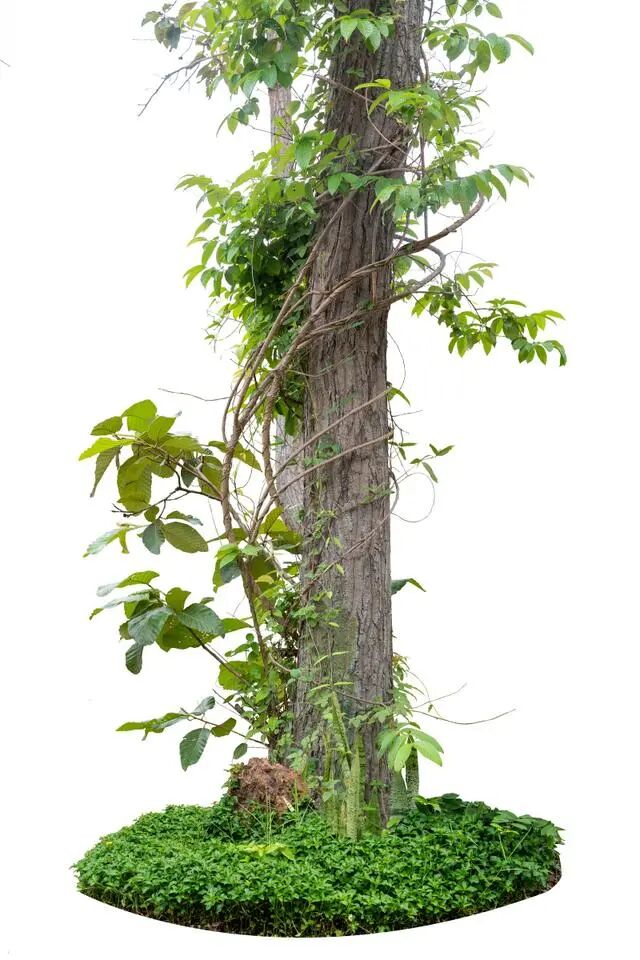
(1) Biological companion planting is fairly easy to grasp. Take vines — climbing plants that must lean on something else in order to climb upward or to creep along the ground. The trunk of a tree is the vine’s natural companion and partner (the image of vine and tree entwined is exactly what people use to describe romantic love). Vines are usually rich in medicinal value. Let us look at which vines are common in the north and in the south.
Northern China (North China, Northeast, Northwest) Oriental bittersweet (Celastrus orbiculatus) Distribution: hillside thickets in the Northeast, North China, and the Northwest; often twining around trees or rocks. Medicinal value: the whole plant is used — root, vine, leaf, and fruit are all usable. Properties: dispels wind and dampness, invigorates blood and resolves toxin; treats rheumatoid arthritis, traumatic injury, and venomous snakebite.
Southern China (South China, Southwest, and the Yangtze River basin) Smilax (Jingangteng, Smilax china)
Distribution: hillside open woodland in Hunan, Guangdong and Guangxi; the rhizome spreads laterally underground and is often found alongside trees. Medicinal value: the root tuber serves as both medicine and food. Properties: dispels wind and drains dampness, resolves toxin and disperses abscess; simmered in soup it clears heat and dampness (for example, with pork ribs).
Climbing hydrangea (Pileostegia viburnoides) and Pileostegia tomentella Distribution: valley forests in East China, South China, and the Southwest; clings to trees or rocks. Medicinal value: the root is used as medicine; a closely related species is known as the “tumor-dispersing vine.” Properties: dispels wind and dampness, dissipates blood stasis and relieves pain; in Yao medicine it is used as an adjunct in tumor treatment and for rheumatic numbness.
Guyangteng (Ma Lian’an, Streptoculon griffithii) Distribution: wild hillsides in Guangxi and Yunnan; twines around trees. Medicinal value: the root is used in Zhuang medicine, where it is called “Gaeumbe.” Properties: clears heat toxin and removes damp-heat; treats colds, diarrhea, dysentery, edema, and eczema.
Vines usually do not harm the trees they grow on, but when companion planting is deliberately cultivated, balance still has to be watched. After all, they share one roof — the same sunlight and rain — and once that balance tips, the forest is ruined.
Vines are not an especially short-cycle income crop: they generally need about 3–5 years, depending on the species. But compared with timber plantations that run to a decade or more, they remain a medium-cycle product worth pairing in.
Another, more controversial way of generating short-term returns from the trunks of large-diameter timber is parasitism or invasion.
Take burl wood from small-leaf red sandalwood: it forms when the trunk is physically damaged and then scars over — and it sells for a startlingly high price.
Or take the tree-clasping fern that grows in Yunnan, Hainan, and Guangdong — the name itself tells you it lives by clinging to trees.
In Yunnan there are cultivation methods for fu-ling that parasitize living Simao pine, but they are discouraged because they cause the pine to grow poorly.
Modern biotechnology can also establish parasitism between many kinds of microorganisms and the trunk, including insects, mushrooms, fungi, and more. Some of these have short cycles and high value — artist’s conk, sulfur shelf, Chinese gallnut, and others. Here too, close attention should be paid to the effect on the health of the tree itself.
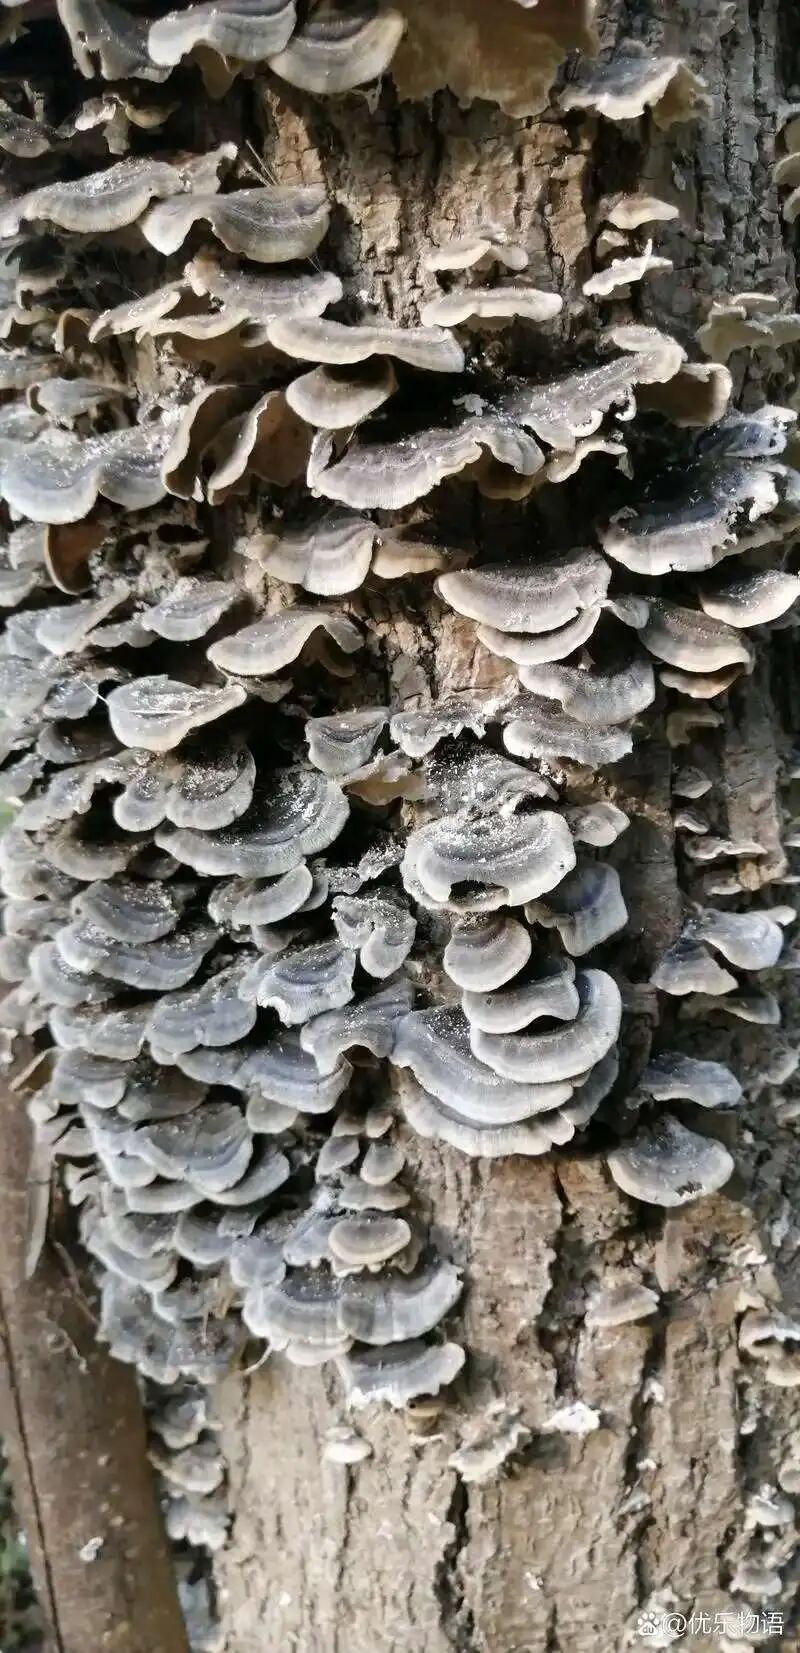
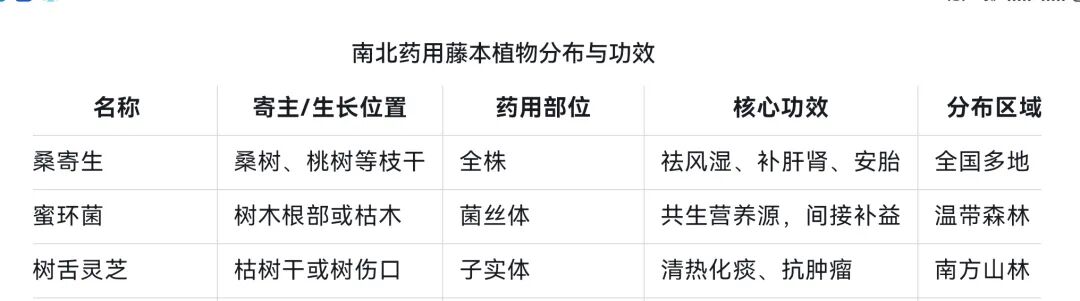
A few common cases are listed below; draw your own inferences from them.
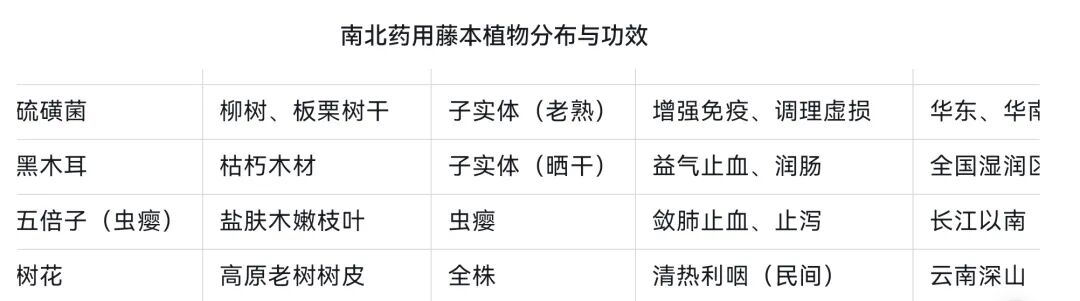
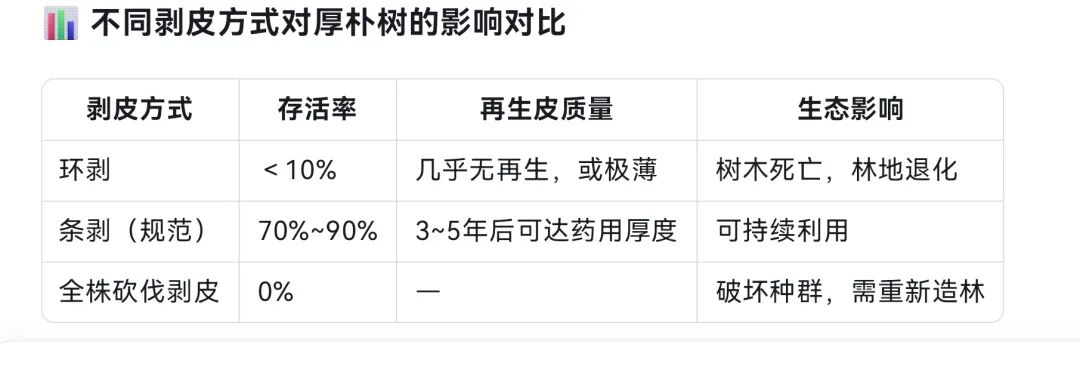
(2) Stem extraction. The common examples are tapping rubber trees for latex and drawing sap from birch trees. Both usually require five years or more before latex or sap can be taken, so they hardly count as short-cycle business lines either. The bark of some tree species also carries a distinctive bioeconomic value. Take Magnolia officinalis (houpo), a timber species common in the Southwest: its bark is a traditional Chinese medicine, and we are now developing extracts from it as a biologic to prevent metastasis in cancer aftercare. But bark is the tree’s vital nutrient conduit and protective layer, and it can only be harvested under strict scientific design and protection (think about what would happen if all your skin were stripped off — a plant is no different).
(3) Creating short-term returns through financial instruments
Finance belongs to the fictitious economy (the fictitious economy is a product of the virtualization of the economy, whose core feature is capital-based pricing). That gives us a hint: in a financial transaction, delivery of the physical good does not necessarily have to be bundled in. Futures trading is the classic case — during the transaction the product has not even been produced yet.
And the reason timber counts as a long cycle under the traditional real-economy trading model is that we must wait for it to weather a decade or even decades and reach full growth before it can be delivered in full.
So let us imagine a “relay baton” trading model: with each step up in asset value (20%, say) as a milestone, the tree growth cycle is split relay-baton style, much as venture capital does with an innovative company — angel, pre-A, A, B, and C rounds, right through to final growth and completed delivery.
But one thing has to be made unmistakably clear here: “asset value rises 20% every five years” is not the same as “every investor earns 20%.” Relay investment only works if, at each handover, someone is willing to take the baton at the new valuation. The real question therefore shifts from “will the tree grow?” to “will the market be willing to buy your tree at that valuation?” The first is a forestry question. The second is a financial one — and it is the second that decides whether this model holds.
Compared with corporate venture capital, forest relay investment has the advantage that the biological growth of the timber asset is monitorable and auditable — the trees grow thicker and taller every year, branches and leaves flourish, birds and insects move in, and remote sensing plus sample plots let you check it year by year. The disadvantage is that the final return lacks the imaginative upside of a company going public. What is monitorable is the biomass; whether market value rises in step is a separate question.
Below we run this model on a very common long-cycle species: masson pine, over 25 years.
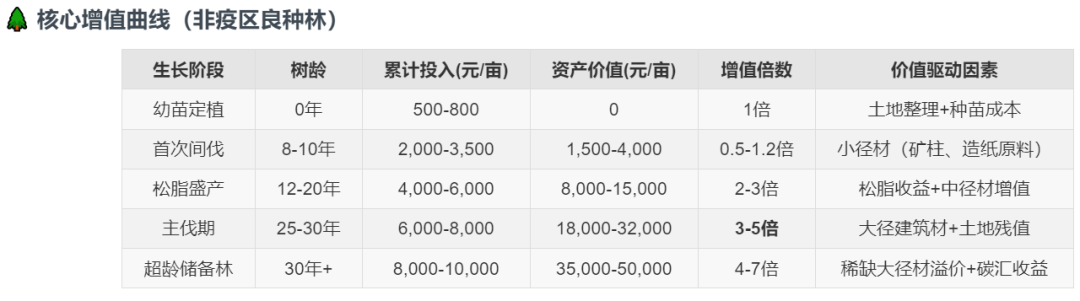
In other words, from the initial investment to year 25 the asset appreciates fivefold (500%) — after deducting establishment and tending costs; otherwise it would be seventeenfold.
Be careful with the units here: fivefold is a total multiple, not an annual return. Fivefold over 25 years is roughly 16% a year on a simple pro-rata basis (400% ÷ 25 years), but on a compounding basis (IRR) it is only about 6.6% — neither of which is anywhere near 20%. Dividing a total gain by the number of years and calling it “annual” is the most common — and most misleading — slip in this kind of projection.
And the reason forestry has not been favored by capital in the past is its long-cycle trading characteristic, not a shortage of return.
So if we can design and issue a compliant financial product (asset securitization) and, across the 25-year cycle of the masson pine, find investors willing to enter relay-baton style every year, then an asset that could originally only be realized after 25 years gains the possibility of being transferred, and cashed out in stages, along the way.
But make no mistake: being transferable is not the same as being able to promise a return. Whether the baton keeps being passed depends on how the stand actually grows, where timber prices actually go, and how each next holder judges the future valuation. That is why, in our projections and in everything we publish, we keep four mutually non-interchangeable metrics strictly apart:
- Biological growth rate — annual volume increment of the stand; a physical metric (4.2%, say)
- Timber market value growth rate — the combined effect of timber prices and stand quality; a market metric
- Project operating IRR — the investment metric computed from real operating cash flows: timber, understory, spatial use
- Secondary-market transfer return — the trading metric formed by one holder’s buy price and sell price
None of these four may stand in for another, and none may be used to imply that a forest “naturally yields 20% a year.”
So what do we need to do? Three things:
-
Build a trustworthy, professional team capable of carrying out perpetual forest management, so that the market believes this masson pine forest will grow smoothly to merchantable size and complete its final delivery transaction.
-
Establish a complete, integrated space-air-ground digital forest asset monitoring platform that is visible, trustworthy, and auditable — so that investors and potential traders can see in real time that the forest is intact and watch the natural growth of this living asset.
-
Build a unified futures-and-spot trading market for physical timber, so that the market believes the timber will be easily realizable once it reaches merchantable size at 25 years, and build a digital financial asset trading platform (RWA) where relay investors can enter and trade.
These three tasks are exactly the priorities we are working to deliver.
In the next installment we begin exploring short-cycle models in the understory economy — a key area that everyone is watching closely.